
Health Insurance in Indiana for Individuals, Families and Business Owners
You have more options than you think. Indiana uses HealthCare.gov, and Open Enrollment for 2027 runs November 1, 2026 to January 15, 2027. Creative Health Solutions compares Marketplace plans, private plans, small business group plans and life insurance with you by phone or Zoom video. There's no cost to talk to us.

You have more options than you think
Picture a couple outside Fort Wayne, both in their late 50s, running a landscaping business from home. (A hypothetical, not real clients.) In November they open HealthCare.gov, see their 2027 price and figure that's the only number.
It isn't. Most people in Indiana think HealthCare.gov is the only place to look. It's one door. There are others: private plans and, for business owners, group plans. And for 2027 the savings cap is back.
Make too much for help, still paying full price? That's the middle-class squeeze.
For 2026, 300,049 Hoosiers picked a Marketplace plan (CMS). Darius Mills and our team put every door side by side. We compare plans from carriers across Indiana.

Marketplace plans and your 2027 savings
Marketplace (ACA) plans are sold on HealthCare.gov. A premium tax credit (savings that lower your monthly premium) depends on income.
What changes for 2027
- The yardstick: savings use the 2026 federal poverty level (FPL), an income yardstick: $15,960 for one person, $33,000 for a family of four.
- The cap: savings generally stop above 400% of FPL: $63,840 for one person, $132,000 for a family of four.
- Immigration status: from January 1, 2027, savings go only to citizens, nationals and certain noncitizens, such as green card holders. Many other lawfully present immigrants can still buy a plan without the credit (full list).
On a lower income? The Healthy Indiana Plan (HIP), Indiana's Medicaid program for adults 19 to 64, may be an option. We can point you there.
Private plans outside the Marketplace
These come straight from an insurer, with no tax credits. PPOs are available on some Indiana private plans, though networks vary by plan. Some ask health questions and may not cover every ACA benefit or pre-existing conditions. Above the cap or past Open Enrollment? One may be worth a look. Private plans can start as soon as next month, though approval and rates aren't guaranteed. Darius shows you what each covers and leaves out.

Coverage for your family
Cheapest isn't always the point. Compare the yearly total (premium, deductible and out-of-pocket maximum), not just the monthly bill. Read how individual and family plans work. Kids up to 19 may qualify for low-cost coverage through Hoosier Healthwise, which includes Indiana's CHIP.
Self-employed in Indiana
When you work for yourself, nobody's handing you benefits. Nobody's setting it up for you. Nobody's checking your math.
Options include Marketplace, private or, with an EIN, group plans. Qualifying varies. On HealthCare.gov, report net income, meaning profit, not gross sales, and update it when things change. Guess too low, and you may pay credits back at tax time.
Tax questions go to a tax professional. For tax help, our tax partner Empire 360 offers individual and self-employment tax preparation.

Small business group plans for 1 to 100+ employees
Under Indiana law, a small employer for ACA-compliant group plans generally has 1 to 50 employees. Bigger teams get help too; Darius confirms headcount on a call.
We can help with any of these if it's the right option for your team: a traditional group plan; a MEWA (multiple employer welfare arrangement), where small employers join one larger plan; a level-funded plan; a PEO (professional employer organization), which handles HR and lets small businesses join its benefits plan; or an ICHRA, a set monthly amount toward each employee's own individual plan. See how we help small businesses.
Life insurance, added to your health review
Term life covers a set number of years, often matched to the mortgage or the kids' years at home. Final expense is a smaller permanent policy for funeral costs; some wait a few years before the full benefit pays. Owners can add group life. Indexed universal life (IUL) is permanent coverage, not an investment. The insurer makes the final decision. More on our life insurance page.
How we work with Indiana clients
Book a call, we compare your options, we apply together.
- Book a call by phone or Zoom video.
- We compare your options.
- We apply together.
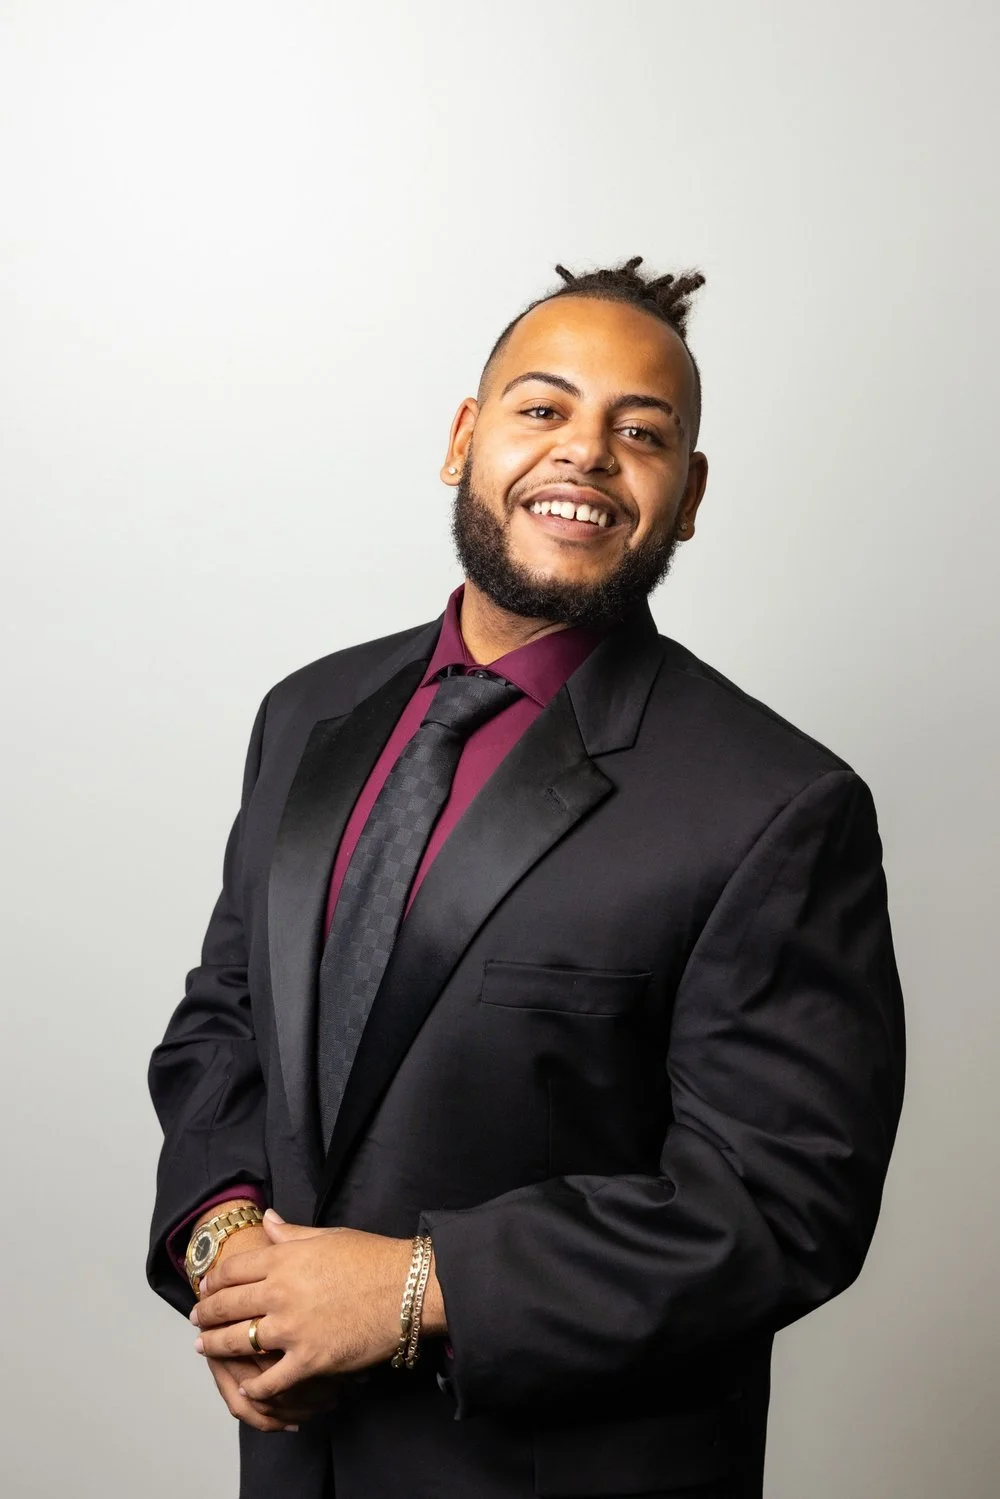
Creative Health Solutions is based in Melbourne, Florida. We work with Indiana clients by phone or Zoom, and Darius is licensed in all 50 states. We understand how overwhelming insurance options can be. Darius founded the agency, and the team has over 10 years of combined experience.
Talk with Darius, Fred, Matthew, Chris or Alex Guerrero. Prefer Spanish? Alex, a newer broker on our team, speaks Spanish. See Darius's story and meet the team.
Call (321) 872-4940, Monday to Friday, 9 AM to 5 PM ET; after that, by appointment only. No cost to talk, no broker fees. Contact us or see more health insurance questions.
Indiana health insurance FAQ
Does Indiana use HealthCare.gov?
Yes. Indiana's Marketplace runs on HealthCare.gov, and 300,049 people in the state picked a plan there for 2026. It isn't the only route. Private plans and, for business owners, group plans are options too. We compare them with you at no cost.
When is Open Enrollment in Indiana for 2027?
November 1, 2026 to January 15, 2027. Sign up by December 15 for coverage starting January 1, or by January 15 for February 1. Later in the year, a qualifying life event can open a Special Enrollment Period, and private plans may be another route.
Who qualifies for Marketplace savings in Indiana for 2027?
Generally, households earning 100% to 400% of the federal poverty level: using the 2026 guidelines, $15,960 to $63,840 for one person and $33,000 to $132,000 for a family of four. Above 400%, savings generally stop for 2027. Hoosiers with lower incomes may qualify for the Healthy Indiana Plan instead.
Can lawfully present immigrants still get ACA tax credits in Indiana in 2027?
Some can. Starting January 1, 2027, savings go to citizens and nationals, green card holders, Cuban or Haitian entrants and COFA migrants, if otherwise eligible. Many other lawfully present immigrants can still buy a Marketplace plan at full price or look at private plans.
What are my health insurance options if I'm self-employed in Indiana?
You can buy a Marketplace plan based on a careful estimate of your net income, compare private plans, or, if your business has an EIN, look at group options, where qualifying varies. Report profit, not gross sales. Tax questions go to a tax professional.
What counts as a small business for group health insurance in Indiana?
Under Indiana law, a small employer for ACA-compliant group health plans is generally one with 1 to 50 employees. Counting rules vary, so Darius confirms your headcount on a call. Larger businesses get help too: we compare group options for teams of 1 to 100+.
Can I add life insurance when I review my health plan?
Yes. On the same call, we can look at term life for your income and mortgage, final expense coverage for seniors, and group life for business owners. Most policies ask health questions, and some need an exam. The insurer makes the final decision.
Can you help with Medicare in Indiana?
Yes. If you're turning 65, we can help you compare Medicare options by phone or Zoom video, and there's no cost to talk to us. Call (321) 872-4940 or fill out the quote form, and we'll find a time that works for you.
Do you have an office in Indiana?
No. Creative Health Solutions is based in Melbourne, Florida, and works with Indiana clients by phone or Zoom video, with no in-person meetings. Darius Mills is licensed in all 50 states, and Alex on our team speaks Spanish. There's no cost to talk to us and no broker fees.
See your Indiana options
Want to see your options before January 15? Fill out the quote form to request the most up-to-date options for your situation.
 Creative Health Solutions